Aave's native Bitcoin lending plan clears preliminary vote, liquidation risks remain
In brief
- Aave's preliminary ARFC vote drew 100% support on Nov. 9, according to Babylon Labs.
- BTC collateral would stay locked on Bitcoin, with an Ethereum accounting record letting Aave V4 recognize it.
- Core Hub stablecoin credit lines are set at $8 million each for USDT and USDC under the proposal.
- LlamaRisk recommended a 78% collateral factor; liquidations would seize whole vaults.
- Babylon's late-2026 mainnet target remains conditional and subject to change.
How the vaults would work
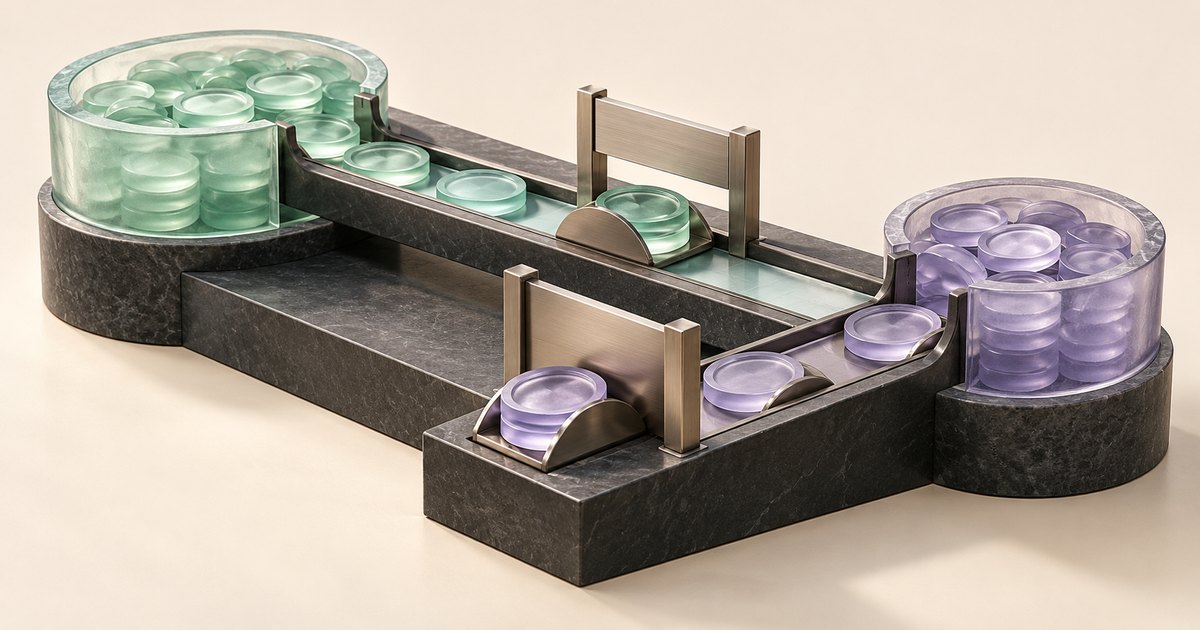
Under the proposed change, BTC would stay locked on Bitcoin, and an Ethereum-based accounting record would let Aave recognize it. Borrowers wouldn't need to supply a freely transferable wrapped Bitcoin token. The record itself (a transfer-restricted ERC-20 accounting unit) couldn't be borrowed. It represents BTC securing a position.
The governance proposal sets out initial Core Hub stablecoin credit lines of $8 million each for USDT and USDC, $1 million for GHO and $2 million each for USDG and RLUSD. CryptoSlate described those limits as proposed capacity. A separate pool, the Babylon Hub, would let liquidity providers choose exposure to native Bitcoin collateral, with its own limits. Risk adviser LlamaRisk recommended a 78% collateral factor for native BTC.
Where the liquidation risk sits
CryptoSlate's analysis puts it plainly.
Keeping the underlying BTC on Bitcoin does not remove liquidation or settlement risk.
Borrowers could still lose vault collateral through liquidation. Under the permissionless route, BTCVaultSwap would borrow WBTC from an Aave Hub to settle immediately with liquidators. Permissioned arbitrageurs would later repay that debt and redeem the underlying BTC over several days, according to LlamaRisk's assessment. The proposed Core Hub draw cap for that settlement venue is 100 WBTC, separate from the stablecoin lines.
Permissioned actors can also liquidate and redeem vaults directly without drawing Hub liquidity, though fees or borrower compensation could still require WBTC. What's the sharper edge for borrowers? As the assessment describes it, liquidation seizes whole vaults, even when clearing the debt takes less than a vault's full BTC value. The borrower is paid discounted compensation for the remainder in wrapped BTC.
What's still ahead
Babylon targets mainnet for late 2026, subject to change and confirmation. It says deployment will start with restrictions on participants and volume, and the schedule and staged rollout plan are still to come. For now, Babylon's FAQ points users to a public testnet and gives a fourth-quarter mainnet target.
There's still an AIP vote, a restricted rollout and a conditional timeline between this ARFC result and live BTC-backed loans on mainnet.
Frequently asked questions
How would Aave's native Bitcoin lending work?
Under the proposal, BTC would stay locked on Bitcoin, and an Ethereum-based accounting record would let Aave recognize it as collateral. Borrowers wouldn't need to supply a freely transferable wrapped Bitcoin token. The collateral record itself couldn't be borrowed.
Is Aave's native Bitcoin borrowing market live yet?
No. The plan passed only a preliminary ARFC vote, and an Aave Improvement Proposal for final on-chain approval comes next. Babylon targets mainnet for late 2026, subject to change and confirmation. Its FAQ currently directs users to a public testnet.
What happens to native BTC collateral in a liquidation?
Borrowers could still lose vault collateral. Under the permissionless route, BTCVaultSwap would borrow WBTC from an Aave Hub to settle with liquidators, and permissioned arbitrageurs would later redeem the BTC over several days. Liquidation seizes whole vaults, and the borrower gets discounted compensation for the remainder in wrapped BTC.